This market is becoming an investment vehicle for buyers and, for sellers, a response to needs related to increased life expectancy.
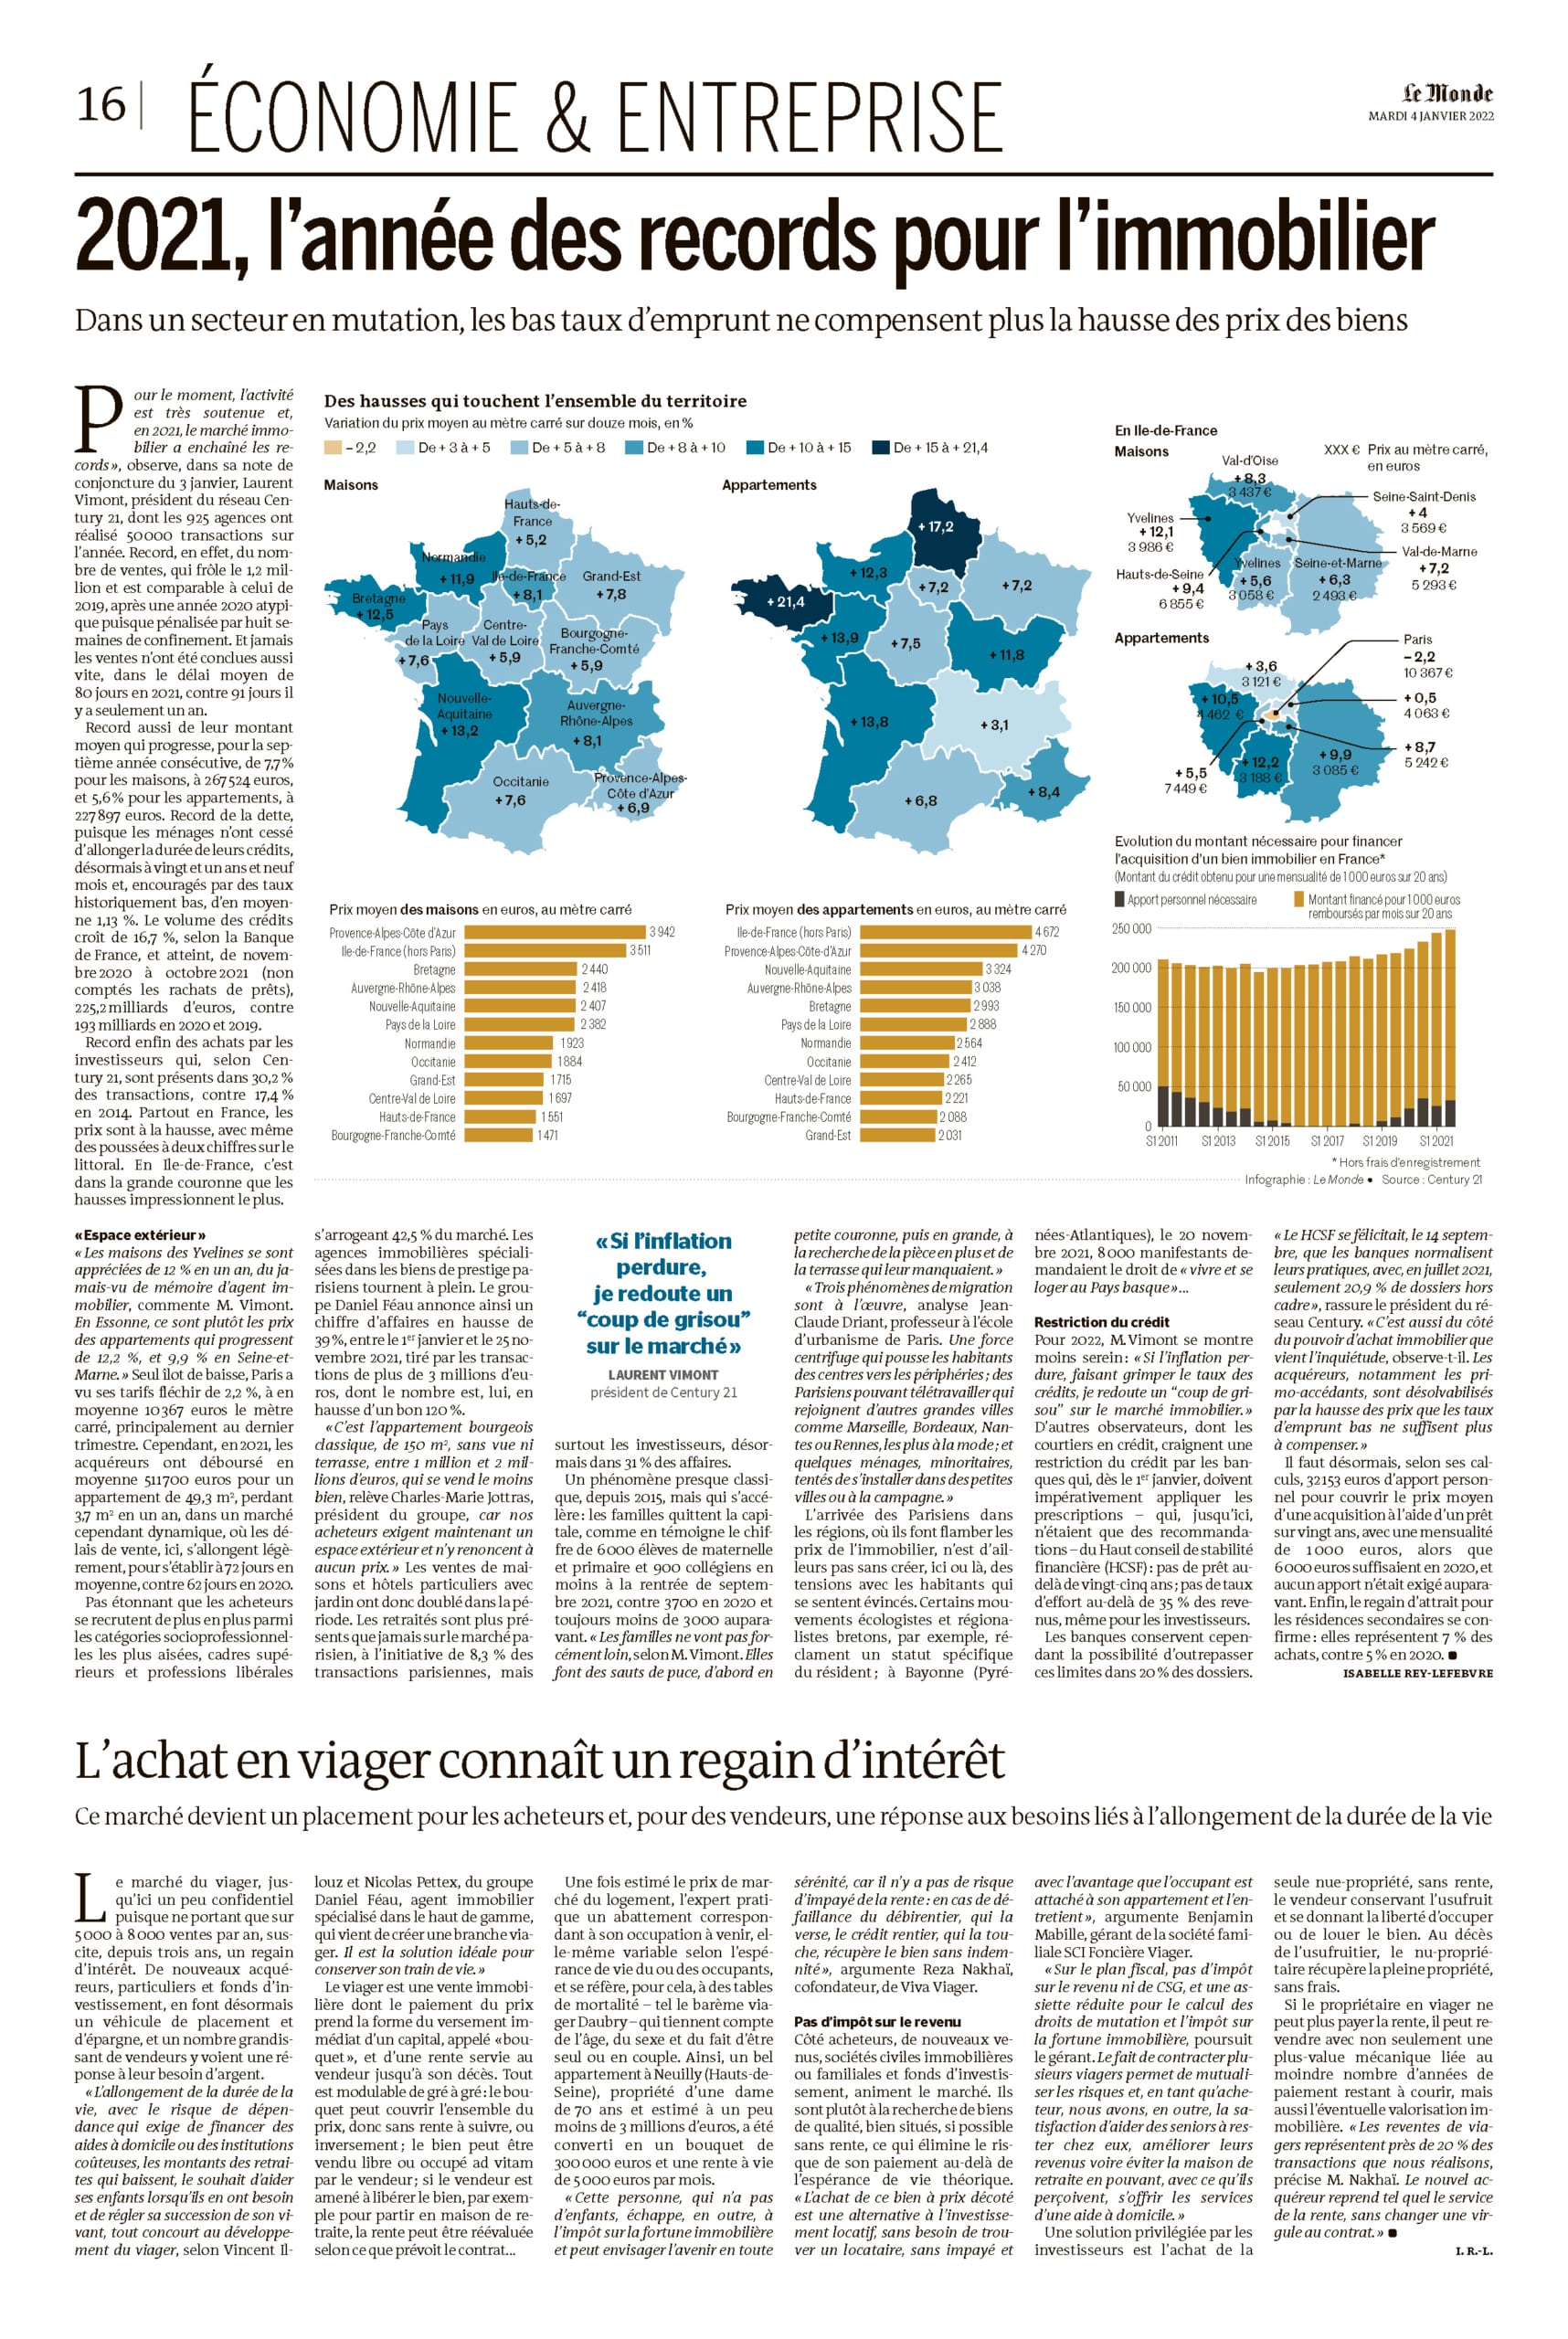
Article published in Le Monde on Tuesday, January 4, 2022. By Isabelle Rey-Lefebvre
The life annuity (viager) market, which until now has been somewhat confidential with only 5,000 to 8,000 sales per year, has seen a resurgence of interest over the past three years. New buyers, including individuals and investment funds, are now using it as an investment and savings vehicle, while a growing number of sellers see it as a solution to their need for liquidity.
“Increased life expectancy, with the risk of dependency requiring the financing of home care or expensive institutions, declining pension amounts, the desire to help children when they need it, and the wish to settle one’s estate while still alive—everything contributes to the development of the life annuity market,” according to Vincent Illouz and Nicolas Pettex of the Daniel Féau Group, a real estate agency specializing in luxury properties that has just created a life annuity branch. “It is the ideal solution for maintaining one’s lifestyle.”
A life annuity sale is a real estate transaction where the price payment takes the form of an immediate lump sum, called the “bouquet,” and an annuity paid to the seller until their death. Everything is negotiable by mutual agreement: the bouquet can cover the entire price, meaning no subsequent annuity, or vice versa; the property can be sold vacant or occupied for life by the seller; if the seller is required to vacate the property, for example to move into a retirement home, the annuity can be revalued according to the terms of the contract…
Once the market price of the home is estimated, the expert applies a discount corresponding to its future occupation, which itself varies according to the life expectancy of the occupant(s). For this, they refer to mortality tables—such as the Daubry life annuity scale—which take into account age, gender, and whether the person is single or part of a couple. For example, a beautiful apartment in Neuilly (Hauts-de-Seine), owned by a 70-year-old woman and valued at just under 3 million dollars, was converted into a bouquet of 300,000 dollars and a life annuity of 5,000 dollars per month.
“This person, who has no children, also avoids the real estate wealth tax and can look to the future with complete peace of mind, as there is no risk of unpaid annuities: in the event of default by the payer (débirentier), the recipient (crédirentier) recovers the property without compensation,” argues Reza Nakhaï, co-founder of Viva Viager.
No Income Tax
On the buyers’ side, newcomers such as real estate investment companies (SCIs), family offices, and investment funds are driving the market. They are primarily looking for high-quality properties in prime locations, preferably without an annuity, which eliminates the risk of paying beyond the theoretical life expectancy. “Buying this property at a discounted price is an alternative to rental investment, without the need to find a tenant, without unpaid rent, and with the advantage that the occupant is attached to their apartment and maintains it,” argues Benjamin Mabille, manager of the family company SCI Foncière Viager.
“From a tax perspective, there is no income tax or social security contributions (CSG), and a reduced base for calculating transfer duties and real estate wealth tax,” the manager continues. “Contracting several life annuities allows for the pooling of risks and, as a buyer, we also have the satisfaction of helping seniors stay in their homes, improve their income, or even avoid a retirement home by being able to afford home care services with what they receive.”
A preferred solution for investors is the purchase of the bare ownership (nue-propriété) only, without an annuity, with the seller retaining the usufruct and the freedom to occupy or rent out the property. Upon the death of the usufructuary, the bare owner recovers full ownership without additional costs.
If the owner of a life annuity property can no longer pay the annuity, they can resell it with not only a mechanical capital gain linked to the fewer number of payment years remaining, but also any potential real estate appreciation. “Resales of life annuities represent nearly 20% of the transactions we handle,” specifies Mr. Nakhaï. “The new buyer takes over the annuity payments as is, without changing a single comma in the contract.”